RSS
|
Sign up here for our free Roundtable Scripts - get this unique intelligence by email as Opalesque publishes them: For anyone dealing with hedge funds or alternative investments, it’s probably worthwhile to remind ourselves where we were in January, February of this year, when a number of investors were asking what the value of hedge funds was, relative to the fees paid to those hedge funds, and what they could get from other products? Fast forward to today, many investors sit back and say, “Well, given the current level of market uncertainty, what has my hedge fund portfolio done for me relative to my other assets? What has my volatility been? Going forward, do I want to own a portfolio of solely long equities and long bonds in an environment where, for example, we have recently seen the entire Japanese yield curve going negative, or should I also own a less correlated portfolio of hedge funds?” Fact is that investors are still very much interested in hedge funds and CTAs. The mainstream press seem to have focused their attention on the few institutional investors who have exited their hedge fund investments, and not those that are increasing or the real reasons behind any of the above decisions. The underlying trend is that many more institutional investors are actually getting with more and more assets into hedge funds. Sure, a number of strategies are up, but what if your hedge funds are down? But it’s also true that investing in hedge funds is a very intensive business, at least doing it properly is. A lot of hedge fund have performed poorly over the course of the last year-and-a-half or so, and many investors had a relatively miserable experience of investing in hedge funds, and they worry that it might be their fault for picking the wrong ones (the trend to direct investing has probably tended to favor investing in the big, brand name hedge funds, which hasn’t always helped). Whoever carried that particular responsibility may not look that smart now, and so quite a few investors are wondering whether they should do it differently as fees on outsourcing this are now much lower, while the cost of doing the work properly is only going up. The expected return on traditional assets, which don’t look great, is forcing many people into alternatives, even if they’re a bit reluctant. The current returns also explain some of the resurgence of interest in non-correlated strategies: The CTA Index is up 4% as of early July, Short-Term Traders Index is up 6%, Global Macro is up 2, Discretionary is down 2, and Volatility Traders are up 4. Institutional investors sitting on a portfolio of pure long equities and bonds are somewhat nervous. There is a lot of interest in these strategies, and also equity market neutral and stat arb. How to make a return without resorting to illiquidity? A majority of liquidity provisions is 90-day liquidity or less, and so the collapse of liquidity provision for people trading less liquid securities, notably single name credit for example, is really striking. All of the liquidity has moved into index trading [see our discussion of ETF trading and consequences on price discovery in our recent France Roundtable]. This means that quite a lot of conventional and very successful hedge fund strategies, for example some of the credit long/short strategies, can only be done on longer time horizons than managers have for their client capital. Managers and multi-managers are shying away from anything that looks less liquid, even though the expected return from it is clearly better. The challenge is how to make a return without resorting to illiquidity? Find out in this Roundtable script how the industry has innovated to get fees down and capital efficiency up to address this key issue. Unstable managers: Fund turnover is the hedge fund investor’s biggest headache The biggest problem with our entrepreneurial industry is the large fund turnover. It’s incredibly hard when you look at the industry now to remember what it looked like in 2006, so just ten years ago. It’s astounding how many of funds have disappeared, and when they disappear they normally take you for a loss at the same time; generally they don’t go out at the top. But if you do the work an underlying pattern becomes visible, and the reality is that there are certain strategies in which the turnover is much higher than others. This Roundtable discusses certain inherent characteristics of strategies and identifies typical blow up strategies and also some that can be much more stable.
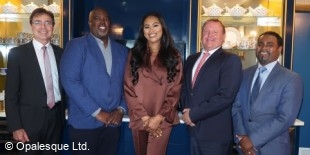
The Opalesque 2016 U.K. Roundtable, sponsored by Societe Generale and Eurex, took place in early July at SG’s London office with:
The Opalesque Roundtable Series offers unparalleled intelligence on the most important global hedge fund jurisdictions and their players. The Roundtable Series is a free publication from Opalesque and is continually updated. Please scroll down to view the full selection of our Roundtables - covering the globe!
Opalesque Roundtable Series - A Catalogue of Intelligence on Global Hedge Fund Centers:
|
|
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||