RSS
|
Sign up here for our free Roundtable Scripts - get this unique intelligence by email as Opalesque publishes them: Co-Investments are equity, debt or other exposures offered by fund managers to their investors directly in the portfolio companies, project or trade in which they invest. They can offer access to high-conviction ideas and differentiated return streams with lower fees and potentially enhanced returns. Co-investments also allow investors to better manage and add concentration in their portfolio and can therefore be an attractive complement to fund investing. The number of co-investments in private equity has grown 20 fold over the last 17 years with about 90% of private equity fund managers offering co-investment opportunities. Co-investment and direct deals have been gaining significant momentum for hedge funds and real estate funds as well. In a 2016 survey, 80% of investors said they exercise co-investment rights at best 'occasionally', 13% using them 'very often', and 6% employing them 'always or almost always'. Over 50% of investors said they shortened their decision making processes, mainly in order to do more co-investment. A recent Forbes article pointed out that private investors with a net worth of $500 million or more are using a significant and increasing part of their wealth to acquire a stake in or whole businesses throughout the world, typically through a direct investment via their single-family offices. For example, many of Pierre duPont's clients don't want to invest in a fund because they recognize that the best way to protect and grow their wealth is to own a substantial chunk of a successful and growing business which ideally is in line with their own operational and entrepreneurial expertise. Still, a large range of investors are receptive to co-investments via an asset manager because the trades are typically complicated and often a host of legal structures are involved. Investors also appreciate and seek the flexibility co-investments are offering, as they can be structured in a wide variety of ways - e.g. segregated portfolio company (SPC), a fund-of-one or a separately managed account (SMA) to meet the needs and preferences of the investor surrounding issues such as custody, investment discretion and confidentiality of their involvement. While we know that the fees and investment returns look good, but the lack of process, organizational structure and difficulties around manager selection are blocking points for many investors. Timing can also be an issue regarding the timely execution of a co-investment, but this can be addressed upfront with prearranged fees and prearranged structures (page 7, 21).
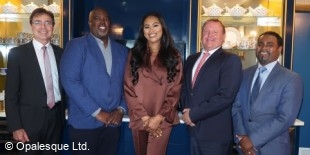
This Roundtable, sponsored by Lyxor Asset Management, took place in New York City with:
The group also discussed:
The Opalesque Roundtable Series offers unparalleled intelligence on the most important global hedge fund jurisdictions and their players. The Roundtable Series is a free publication from Opalesque and is continually updated. Please scroll down to view the full selection of our Roundtables - covering the globe!
Opalesque Roundtable Series - A Catalogue of Intelligence on Global Hedge Fund Centers:
|
|
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||