|
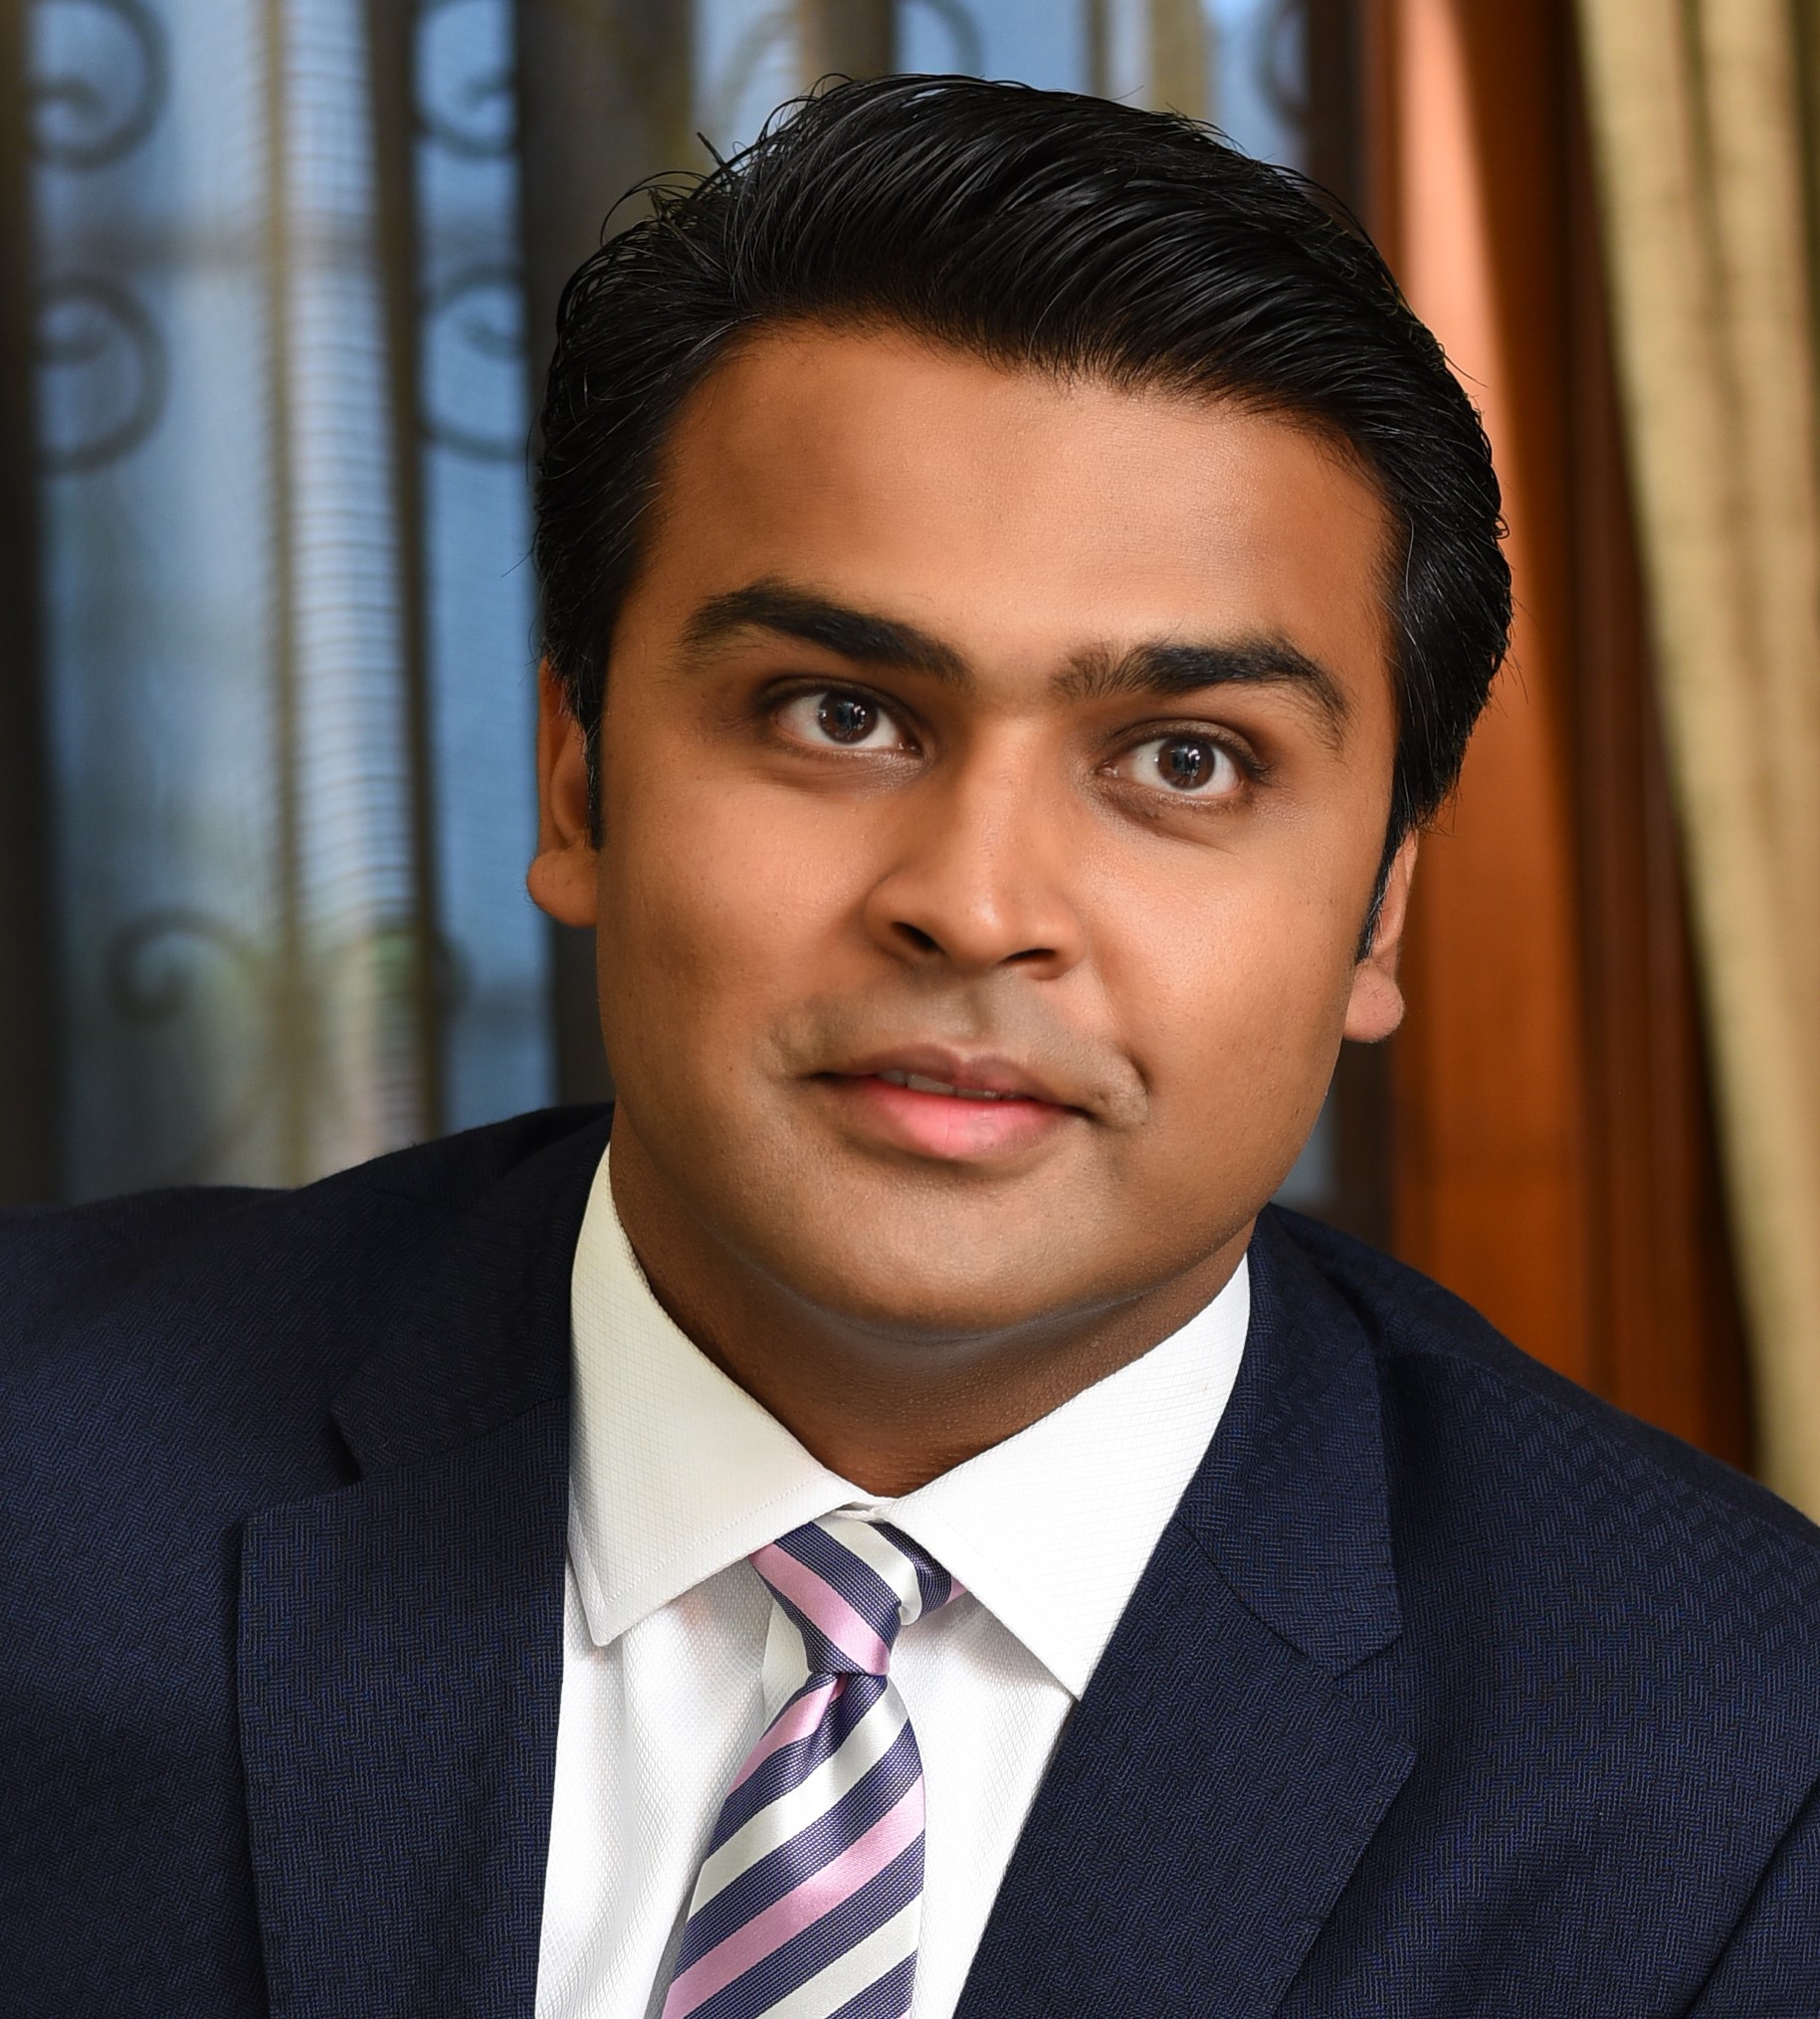
Nishchay Goel Matthias Knab, Opalesque: The world's largest asset manager is calling the next quarter century for India. The latest GDP print just blew past the central bank's own forecast. Foreign direct investment has hit an all-time record. And yet the Indian stock market is one of the worst performers since the beginning of 2025, with portfolio investors pulling out at the fastest pace this century. Ahead of our webinar "India's Foreign Investor Exodus: A Warning or An Opportunity?" on September 24th with Duro Capital, here is the macro picture in full - both sides of it.
The long game: 1.4 billion people and an "era of India"
When investors scan the globe for growth, their gaze increasingly stops at the Indian subcontinent - and it is easy to see why. India is an emerging market with an abundance of growth levers, and above all, it is big. Very big. 1.4 billion people live there, many of them young and well educated, entering their prime earning and consuming years just as much of the developed world - and China - ages.
The bulls have prominent company. Larry Fink, CEO of BlackRock, the world's largest asset manager, went as far as predicting an "era of India" spanning the next 20 to 25 years in a television appearance this February. And the US financial giant is hardly alone in scouting the country for new opportunities.
The trajectory is well mapped: India is currently the fifth-largest economy in the world and is widely expected to advance to third place in the coming years, behind only the US and China. Strategic capital is following the same logic. A deepened partnership with India is a declared goal of the European Union - not least to strengthen independence from China - and investing in India is likely to become a genuine trend among European private investors in the years ahead, not just among institutions.
The latest data: growth is not just strong - it is broadening
The near-term numbers are keeping pace with the long-term story. According to the September 2026 India Report from London-based Lalcap, authored by veteran India watcher Deepak N. Lalwani OBE, India's economy grew 7.8% in the April-June quarter - easily beating the Reserve Bank of India's own 7% forecast, and against an RBI pre-data projection for FY27 of just 6.7%.
More important than the headline, Lalwani argues, is the composition. Manufacturing expanded 9.2%, services grew around 10%, and household consumption rose 7.1%. But investment stole the show, surging 11.9% and lifting Gross Fixed Capital Formation to 34.3% of GDP, from 31.4% a year earlier. In Lalcap's reading, years of public infrastructure spending are finally beginning to attract private capital that had previously stayed on the sidelines - visible in stronger corporate balance sheets, rising bank credit, and new commitments in semiconductors, data centres, infrastructure and advanced manufacturing.
The significance is structural: if private capex keeps replacing the government as the marginal source of demand, India could be shifting from a state-led recovery into a self-reinforcing, private-investment-led cycle - the kind that lifts productivity, employment and potential GDP growth, and that insulates an economy better against global turbulence. Lalcap's caveat is fair: one quarter does not establish a durable cycle, and the evidence to watch over the next two to three quarters is continued double-digit investment growth, capex announcements becoming actual projects, and credit and wage growth.
Long-term strategic capital has already voted. Equity FDI into India reached a record $58.8 billion in fiscal year 2025-26, up 18% year on year, taking cumulative inflows since 2000 to $788 billion - with Singapore, for the first time, overtaking Mauritius as the largest source country.
Now the other side of the ledger
Set against all of this, the scoreboard of India's stock market in 2026 reads like it belongs to a different country. As of early September, the Sensex stands around 76,500 - down 10.2% year to date, and well below its all-time high of 85,836 set back in September 2024. The Nifty 50 is down 8.5%. The rupee has weakened 5% against the dollar this year to around 95. For comparison: Japan's Nikkei is up 29% this year, the Nasdaq 14%, even the UK's FTSE 9%.
And as readers of the first three articles in this series know, foreign portfolio investors have pulled $30 billion out of Indian equities in the first half of 2026 alone - the largest outflow in any year this century, following a record 2025. In our recorded conversation, Nishchay Goel, Founder and CIO of Duro Capital, traced the mechanics: a deliberate RBI-engineered credit slowdown starting late 2023, an earnings deceleration from 25%+ to mid-single digits, and then a second, purely mechanical leg as allocators rotated capital into Korea and Taiwan to chase AI-driven benchmark weights.
The risks, to be sure, have not vanished. Brent crude at over $100, up 60%+ this year on the Middle East conflict, is a real burden for a country importing 90% of its energy - and a key driver of the weak rupee. Geopolitics remains live: Prime Minister Modi has been pressing President Putin toward a path out of the Ukraine war, most recently at the SCO summit, with Putin due in New Delhi for the BRICS summit in mid-September - consequential diplomacy, though not yet decisive. And some economists debate whether recent methodology changes flatter the 7.8% GDP print, even as the government maintains the revised approach is reliable. Lalcap also notes a less comfortable policy implication: growth this robust gives the RBI less room to cut rates aggressively.
The domestic revolution nobody prices in
There is one more structural force that bridges the gap between the booming economy and the abandoned stock market - and it comes from inside India. Less than 5% of Indians actively invest in capital markets today. The traditional savings culture is conservative: cash, bank deposits, and above all gold. But that attitude is beginning to change, and it is the young generation leading the shift - increasingly willing to put money into equities and funds, mostly in their home market.
The flows are already measurable. As Goel points out, Indian households are putting roughly $60 billion of fresh capital into domestic equities every year - effectively absorbing everything foreigners have sold - and still hold only 6 to 7% of household savings in equities, against 40 to 50% in the US. "Imagine it just goes to 12%," Goel told us. "You suddenly have $120 billion coming in every year from domestic capital. We have that structural support for the next 25 years."
Note the symmetry: 25 years of structural domestic equitization on Goel's arithmetic - the same horizon as Fink's "era of India."
Warning or opportunity?
So which is it? A 7.8% economy with record FDI, a broadening private investment cycle, and a domestic savings revolution - or a market that sophisticated foreign investors are exiting at the fastest pace this century, with oil at over $100 and a war on the horizon of every projection?
That is precisely the question we will put on the table - with the data, the portfolio evidence, and your questions - in our live webinar.
Webinar: "India's Foreign Investor Exodus: A Warning or An Opportunity?" - Join Nishchay Goel and Parikshit Shah of Duro Capital live on Thursday, September 24th at 11am ET (4pm UK, 5pm CET, 6pm Riyadh, 7pm Dubai, 8:30pm Delhi). Register here to reserve your place and submit questions in advance: www.opalesque.com/webinar. A replay will be provided to all registrants.
This article is for informational purposes only and does not constitute investment advice or an offer to sell securities. Market data as of September 4, 2026, sourced from the Lalcap India Report. Past performance does not guarantee future results. Investors should conduct their own due diligence and consult with qualified advisors before making any investment decisions.
|


 RSS